Banking, finance, securities, insurance,
 and other services
Last updated: 2026/10/16

HJKI Inc
For over 20 years in Los Angeles, USA, we have been assisting primarily Japanese clients with home purchases, refinancing, and real estate investment loans for non-US residents.
DRE Lic. #01438563 | NMLS ID #240676
Home loans are
From the moment I thought, "Is it still too early?"
You can consult with us
Instead of deciding to "buy" first, considerwhat you can do in the current situationand when it might be possible.
I believe that first, clarifying your current situation is the first step towards finding a safe and secure place to live
Information
| address | 11150 W. Olympic Blvd., Suite 1080, Los Angeles CA 90064 |
|---|---|
| telephone number | 5624773167 |
| kenny@hjkinternational.com | |
| Website | https://kennykimura.zipforhome.com/Home/Index |
List of US mortgage interest rates and other related interest rates [10/16/2026]
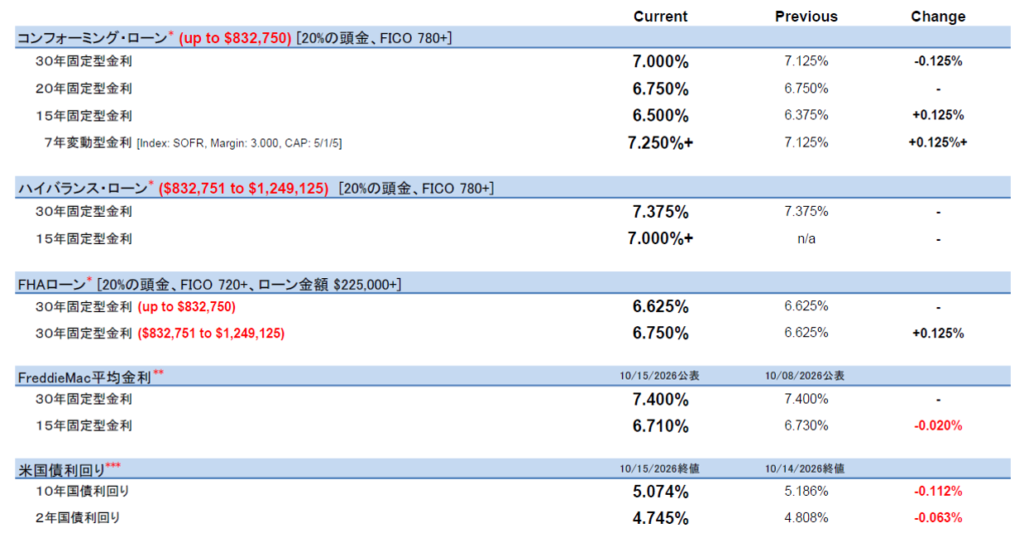
*Conforming loans, high-balance loans, and FHA loans are the rates announced on the day by our partner lenders for home purchase purposes. Rates may fluctuate without notice due to rapid market changes during the day. Rates may also fluctuate based on LTV and FICO score. The rate shown is for a Point of 1. Please contact us if you require a Point of 0.The loan amounts shown are the 2026 maximums for Los Angeles County, Orange County, San Francisco County, and other counties in California. For maximums in other counties,this pageplease refer to
** FreddieMac average interest rates are the figures updated most recently, on Thursday. For more information on previously published interest rates, please see here .**
***US Treasury yields are based on the previous day's closing prices as published by WSJ.com. For more detailed historical yield information,herefor 2-year Treasury bondshereplease see
Real estate investment loans for non-residents in the United States [10/13/2026]
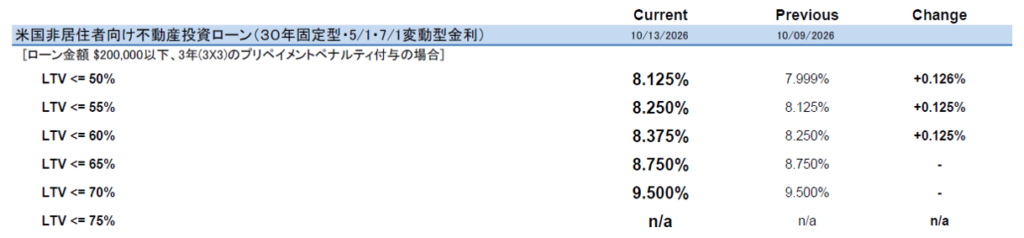
- For investment purposes only; SSN/ITIN not required. No US credit history or FICO score necessary
- Applications can be submitted in the name of an individual, a corporation, a limited liability company, a partnership, or a trust
- Detached houses, condominiums, townhouses/PUDs, 2-4 detached houses
- Minimum loan amount: $100,000 / Maximum loan amount: $3,000,000
- Purchase loan: up to 70% LTV / Refinancing cash-out loan: up to 65% LTV
- No income or employment verification required
- 5-year, 7-year variable rate and 30-year fixed rate
- Interest-only payments are available (initial 5-year/30-year repayment period or initial 10-year/40-year repayment period)
- Inbound financing is required, and loan payments must be automatically debited from a US bank account
Announcement of the 2026 Conforming & High Balanced Loan Cap [11/25/2025]
Today , November 25th, the maximum loan amounts for Conforming Loans and High Balance Loans for fiscal year 2026 were announced as shown in the table below.

This upper limit is published for each county across the United States and is calculated based on the median housing price index from October 1st of the previous year to September 30th of the following year. In most counties across the U.S., the limit for one unit is $832,750 , but some counties in Northern California, such as LA (Los Angeles County), OC (Orange County), and SF (San Francisco County), have higher limits. These fall under the High-Cost Areas shown in the table, with a maximum limit of $1,249,125
In Los Angeles and Orange County, the maximum amount per unit last year was $806,500 and $1,209,750 respectively, so this represents an increase of approximately 3.25%. For information on the maximum amounts for each county across the United States, please refer to this link
Loans up to the amount in the Baseline column are called conforming loans , and loans exceeding that amount up to the amount in the High-Cost Area column are called high-balance loans (also known as conforming jumbo loans), but the basic screening guidelines are almost the same. However, the interest rate for high-balance loans is about 0.500-0.750% higher.
For example, if you purchase a property worth $1,025,000 with a 20% down payment and a loan amount of $820,000, purchasing it in 2025 would result in a high-balance loan . However, purchasing it next year, in 2026, would qualify as a conforming loan , allowing you to purchase it at a lower interest rate. This increase in the upper limit means that there will be more opportunities to purchase higher-priced properties at lower interest rates.